This is the first BalkanHome.eu report built on a time series rather than a single snapshot. Since 30 June 2026 we have recorded every active apartment-for-sale listing in Albania once a day, so for the first time we can say not only what the prices are, but how they moved over a quarter. We compare 1 July with 1 October 2026 and show the monthly path in between. All figures are asking prices, not transaction prices. The cross-sectional picture of the whole market, including houses, land and the comparison with Montenegro, is in our September 2026 report.
Key findings
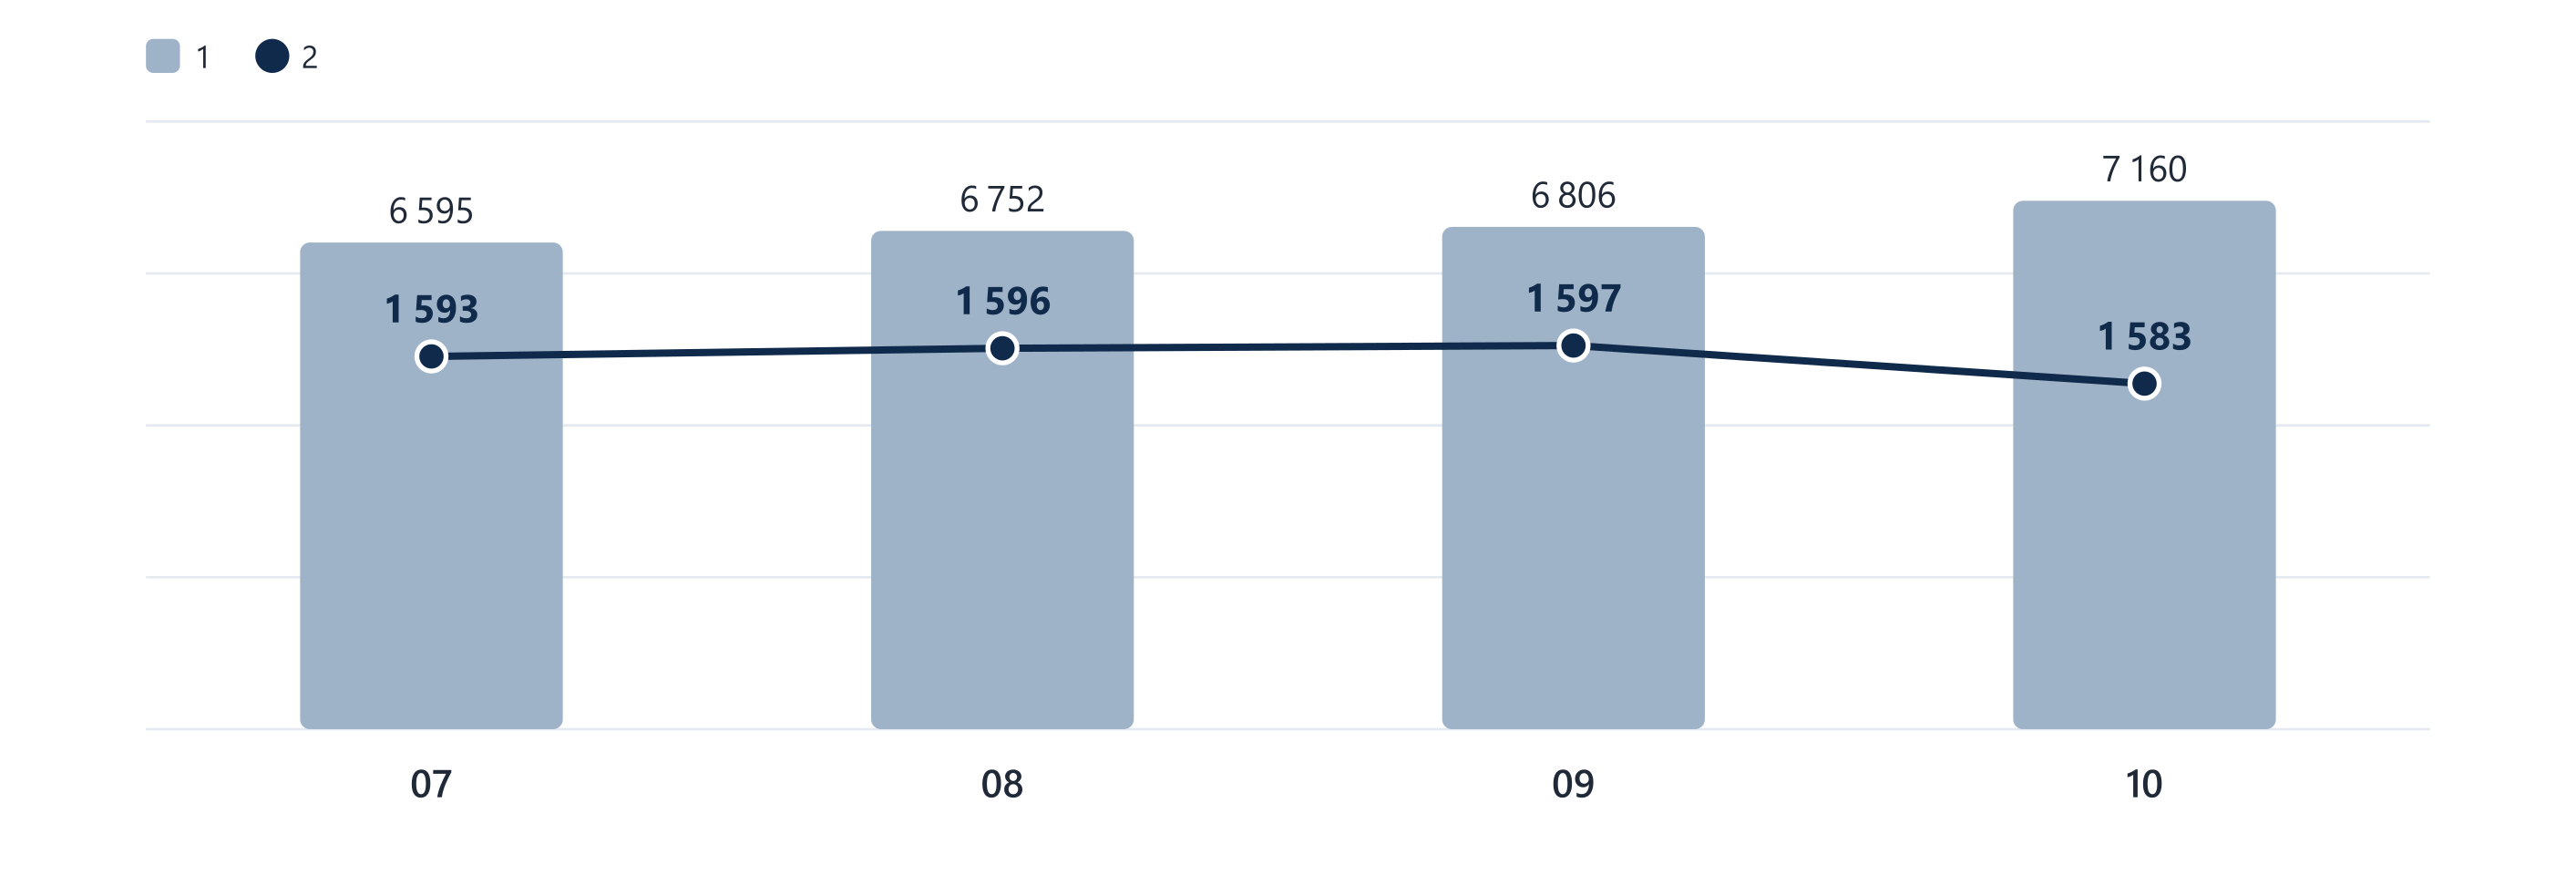
- Asking prices did not move. The national median was €1,593/m² on 1 July, €1,596 on 1 August, €1,597 on 1 September and €1,583/m² on 1 October: a change of -0.6% over the quarter, within the noise of a changing mix. The lower quartile stayed at €1,250/m²; the upper quartile slipped from €2,143 to €2,101/m².
- Supply grew by 8.6%. Active apartments for sale went from 6,595 to 7,160. Over the quarter 754 listings appeared and 189 were withdrawn; 6,406 were on the market on both dates.
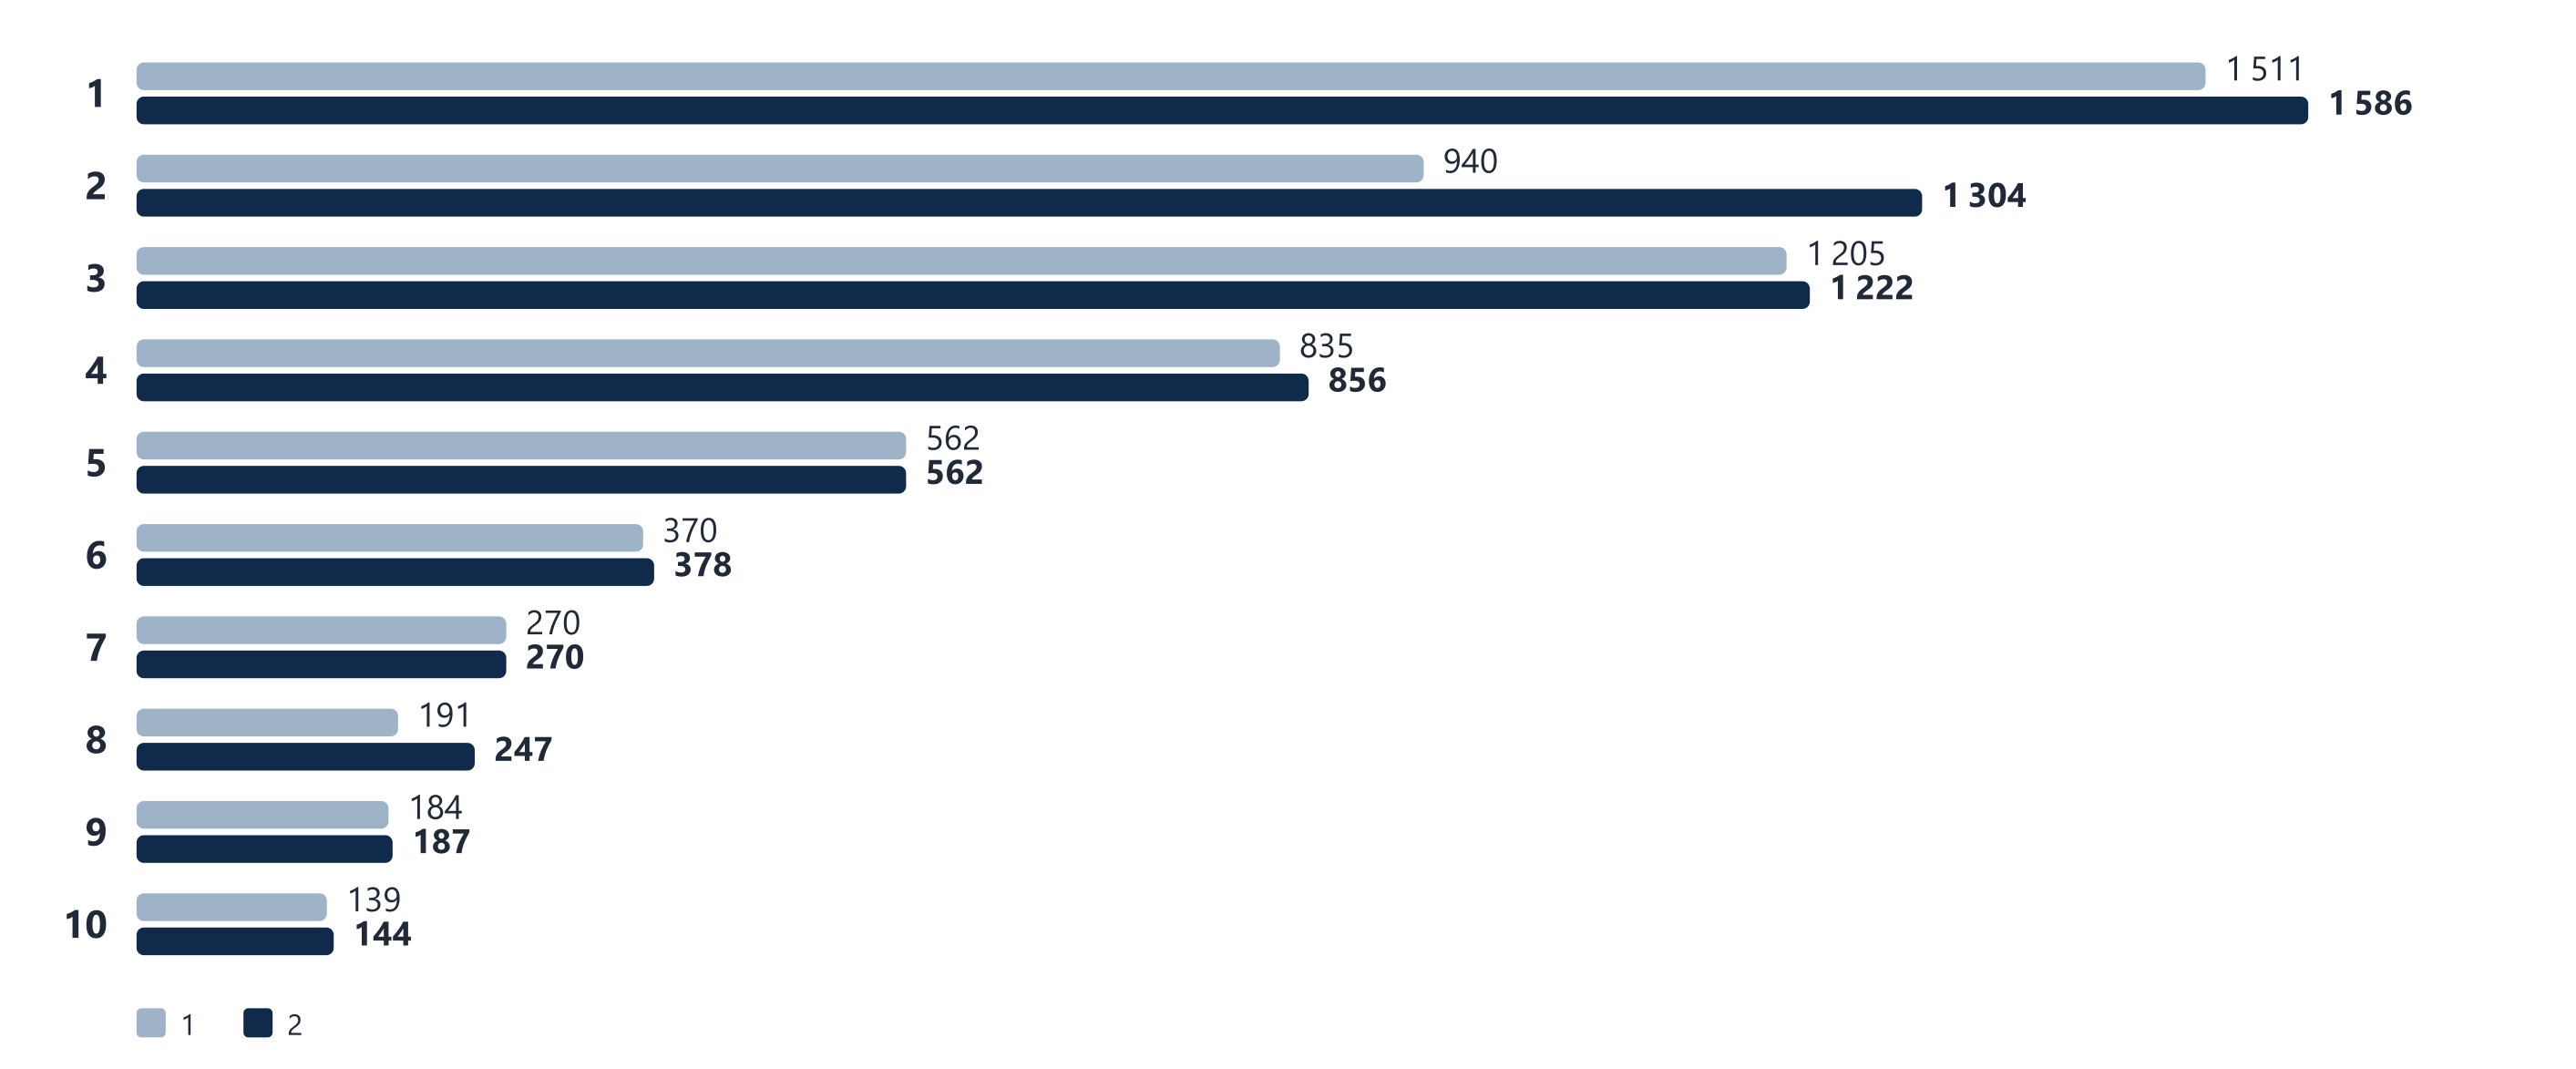
- Nine in ten new listings are on the Bay of Durrës. Golem and Mali i Robit added 390 listings, Durrës city 206 and the Kavajë coast (Qerret, Spille) 79: together 675 of the 754 new listings. Golem alone grew by 39%, from 940 to 1,304 active listings, with the median unchanged at €1,350/m².
- New supply is priced below the stock. Listings that appeared during the quarter have a median of €1,510/m², against €1,596/m² for listings present on both dates. The small dip in the national median is a change of mix, not a repricing of existing apartments.
- Sellers almost never change the price. Of 5,537 listings with a price on both dates, 98.8% kept it. 35 (0.6%) were cut, by a median of 7.6%; 29 (0.5%) were raised, by a median of 6.2%. In Albania a listing that does not sell is withdrawn or left as it is, not discounted.
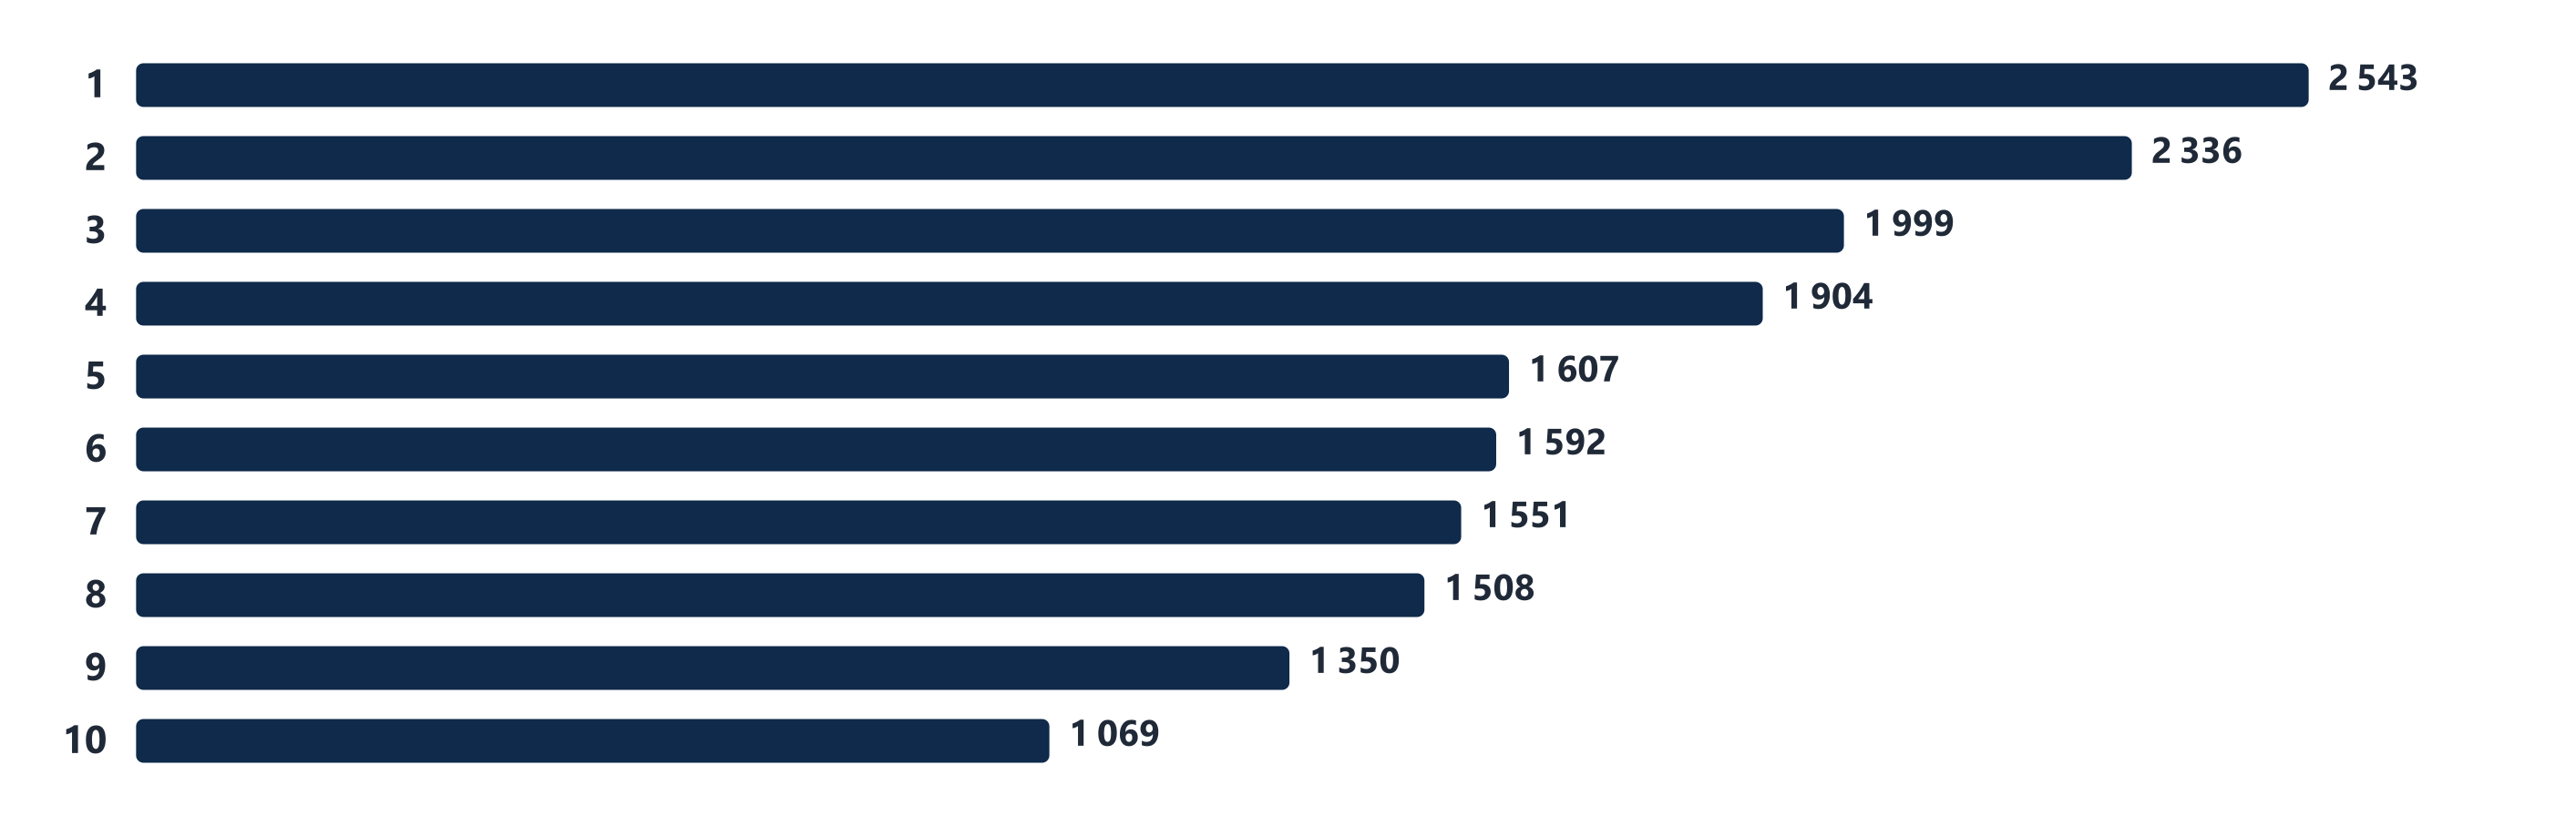
- The Riviera stays in its own league. Dhërmi, Himarë and Vuno: €3,314/m² (N = 52), 2.2 times the Durrës median. Vlorë city €2,543/m², Tirana centre and Blloku €2,336/m², Sarandë and Ksamil €1,904/m² (+2.0% over the quarter).
- A declared sea view costs 26% more per square metre: €1,921/m² against €1,520/m² without one (1 October, N = 828 and 5,395).
Prices over the quarter: flat line, growing bars
The chart shows the month-by-month state of the market on the first day of each month: the number of active apartments for sale (bars) and the median asking price per square metre (line). The median moved by a few euros a month and ended the quarter €10 lower than it started, while supply rose every month and jumped in September.

In numbers: €1,593/m² on 1 July (N = 5,718 listings with a complete price and floor area), €1,596 on 1 August (N = 5,845), €1,597 on 1 September (N = 5,902) and €1,583/m² on 1 October (N = 6,223). The median asking price of an apartment fell from €127,521 to €125,000 (-2.0%), again a mix effect: the new supply on the Bay of Durrës is smaller and cheaper than the average listing.
Note: a snapshot counts every listing active on BalkanHome.eu on that day. Listings without a price or floor area are counted in supply but excluded from the price medians.
Where the new supply comes from
Of the 754 listings that appeared between 1 July and 1 October, 675 (90%) are on the Bay of Durrës: Golem and Mali i Robit (390), Durrës city (206) and the Kavajë coast with Qerret and Spille (79). Tirana, the largest market by value, added a net 38 listings across its districts. Withdrawals were concentrated in Durrës city: 131 of the 189 listings that disappeared.

Golem is the story of the quarter: +39% supply in three months (940 to 1,304 active listings) with a median that did not move from €1,350/m². Developers on the Mali i Robit stretch are releasing new phases at the same price point rather than raising it. The Kavajë coast grew by 29% (191 to 247) and its median rose from €1,543 to €1,592/m² (+3.2%), the largest move among zones with more than 100 listings.
The new listings are priced below the existing stock: €1,510/m² median for listings that appeared during the quarter against €1,596/m² for listings present on both dates. This is what pulls the national median down slightly while every individual zone stays flat.
Sellers do not cut prices
The time series lets us answer a question a single snapshot cannot: what happens to an apartment that does not sell? We matched every listing present on both 1 July and 1 October and compared its asking price on the two dates.
| Price between 1 July and 1 October | Listings | Share | Median change |
|---|---|---|---|
| Unchanged | 5,473 | 98.8% | 0% |
| Cut | 35 | 0.6% | -7.6% |
| Raised | 29 | 0.5% | +6.2% |
| Total with a price on both dates | 5,537 | 100% |
Price cuts are rare everywhere and slightly more common on the coast: 2.7% of matched listings on the Kavajë coast, 1.6% in Durrës city and 1.1% in Golem had a lower price in October than in July. In Tirana, Vlorë, Sarandë and Shëngjin not a single matched listing was repriced downwards. For a buyer this means the asking price is the opening position and the negotiation happens in person, not in the listing.
Price map by zone, 1 October 2026
Zones are assigned from the listing's locality and coordinates (the same zoning as our market intelligence tools). We show zones with at least 39 listings with a complete price and floor area, alongside the sample size, quartiles, median total price and median floor area. The full set, including small zones, is in the CSV file in the media section.

| Zone | Listings 1 Jul | Listings 1 Oct | Median €/m² 1 Jul | Median €/m² 1 Oct | p25 | p75 | Median price | Median area |
|---|---|---|---|---|---|---|---|---|
| Riviera: Dhërmi, Himarë, Vuno | 97 | 99 | €3,311 | €3,314 | €3,018 | €4,107 | €349,000 | 97 m² |
| Vlorë (city) | 370 | 378 | €2,537 | €2,543 | €1,974 | €2,981 | €227,148 | 97 m² |
| Orikum, Radhimë | 39 | 49 | €2,449 | €2,489 | €1,706 | €3,152 | €203,721 | 80 m² |
| Tirana, centre and Blloku | 1,205 | 1,222 | €2,337 | €2,336 | €1,900 | €2,803 | €220,000 | 110 m² |
| Farkë (Tirana) | 270 | 270 | €1,999 | €1,999 | €1,858 | €2,403 | €296,304 | 133 m² |
| Sarandë, Ksamil | 139 | 144 | €1,867 | €1,904 | €1,649 | €2,222 | €152,719 | 80 m² |
| Tirana, outer districts | 835 | 856 | €1,606 | €1,607 | €1,204 | €1,903 | €145,000 | 99 m² |
| Kavajë coast, Qerret and Spille | 191 | 247 | €1,543 | €1,592 | €1,369 | €1,841 | €92,046 | 61 m² |
| Shëngjin, Lezhë | 184 | 187 | €1,550 | €1,551 | €1,485 | €1,709 | €113,460 | 74 m² |
| Durrës (city) | 1,511 | 1,586 | €1,503 | €1,508 | €1,284 | €1,964 | €117,000 | 73 m² |
| Kashar (Tirana) | 85 | 85 | €1,442 | €1,442 | €1,264 | €1,694 | €139,000 | 98 m² |
| Golem, Mali i Robit | 940 | 1,304 | €1,350 | €1,350 | €1,212 | €1,549 | €90,000 | 68 m² |
| Kamëz, Kombinat (Tirana) | 562 | 562 | €1,069 | €1,069 | €900 | €1,197 | €91,000 | 92 m² |
| Korçë | 51 | 54 | €743 | €759 | €631 | €993 | €85,000 | 114 m² |
Three observations. First, the spread between the cheapest and the most expensive zone is 4.4 times (Korçë €759/m² against the Riviera €3,314/m²), and it did not narrow over the quarter. Second, the medians that moved at all moved up: Sarandë +2.0%, Kavajë coast +3.2%, Orikum +1.6%, all zones where new, slightly dearer stock arrived. Third, the cheapest entry into the market remains Golem: a median apartment of 68 m² for €90,000.
What a sea view, a resale and a bigger apartment cost
Three cuts of the 1 October snapshot that matter when reading a listing. Sea view: apartments with a declared sea view have a median of €1,921/m² against €1,520/m² without, a premium of 26% (N = 828 and 5,395). Primary versus secondary market: 79% of active listings are primary-market (developer) stock at a median of €1,553/m²; resale apartments are at €1,649/m², 6% higher, which reflects their location rather than their condition, since most resale stock sits in central Tirana and Vlorë.
| Rooms | Active listings | Median €/m² |
|---|---|---|
| 1 room (studio) | 417 | €1,397 |
| 2 rooms (1+1) | 3,343 | €1,510 |
| 3 rooms (2+1) | 2,623 | €1,644 |
| 4 rooms (3+1) | 528 | €1,902 |
The price per square metre rises with the number of rooms, the opposite of most European markets, where small apartments carry the highest unit price. The reason is location: studios and 1+1 apartments dominate the mass-market coastal developments, while 3+1 apartments are concentrated in central Tirana and in the premium projects on the Riviera.
Method and limits
- Source: daily snapshots of every active apartment-for-sale listing on BalkanHome.eu, recorded since 30 June 2026. The report compares the snapshots of 1 July and 1 October 2026 and shows 1 August and 1 September for the monthly path.
- Prices: asking prices as published by the advertiser, in euros. Listings priced in another currency are converted at the rate of the snapshot day. Price per square metre uses the declared floor area; listings with an area below 15 m² or a price below €10,000 are excluded from the per-square-metre medians as data-entry errors.
- Zones: assigned from the listing's locality text and, where that is missing or unrecognised, from its coordinates. The Riviera zone combines Dhërmi, Drimadhë, Himarë and Vuno.
- Matching: a listing is "present on both dates" when the same listing ID is active in both snapshots. A listing that was withdrawn and re-posted with a new ID counts as withdrawn and new.
- Limits: these are asking prices from a single marketplace, not transaction prices, and the marketplace's mix of advertisers changes over time. Supply figures describe listings on BalkanHome.eu, not the whole Albanian market.
For the media
Charts and data from this report may be used free of charge, crediting BalkanHome.eu as the source with an active link to this report.
Downloads
- Chart: supply and median price, July to October 2026PNG, numbers only, labels in the caption above
- Chart: active listings by zone, 1 July vs 1 OctoberPNG, numbers only
- Chart: median asking price per m² by zonePNG, numbers only
- Report data (CSV)comma-separated, UTF-8 encoded, English column names, all zones
The CSV contains every figure in this report with sample sizes and quartiles, including zones not shown in the tables and the monthly series. Additional cuts (by city, by room count, by price band) are prepared on request for editorial teams.
Media contact: Mateusz Sawicki, founder of BalkanHome.eu · contact@balkanhome.eu